A financial planning process brings a household's goals, income, taxes, investments, and estate considerations into one organized view. For Lehigh Valley pre-retirees, it commonly starts with understanding the full financial picture, then setting priorities, evaluating trade-offs, implementing agreed-upon steps, and revisiting the plan as life and rules change.
What does a financial planning process include?
A financial planning process is not a one-time form or a prediction about the future. It is a structured way to identify the decisions in front of a household, understand how those decisions relate to one another, and establish a process for reviewing them over time.
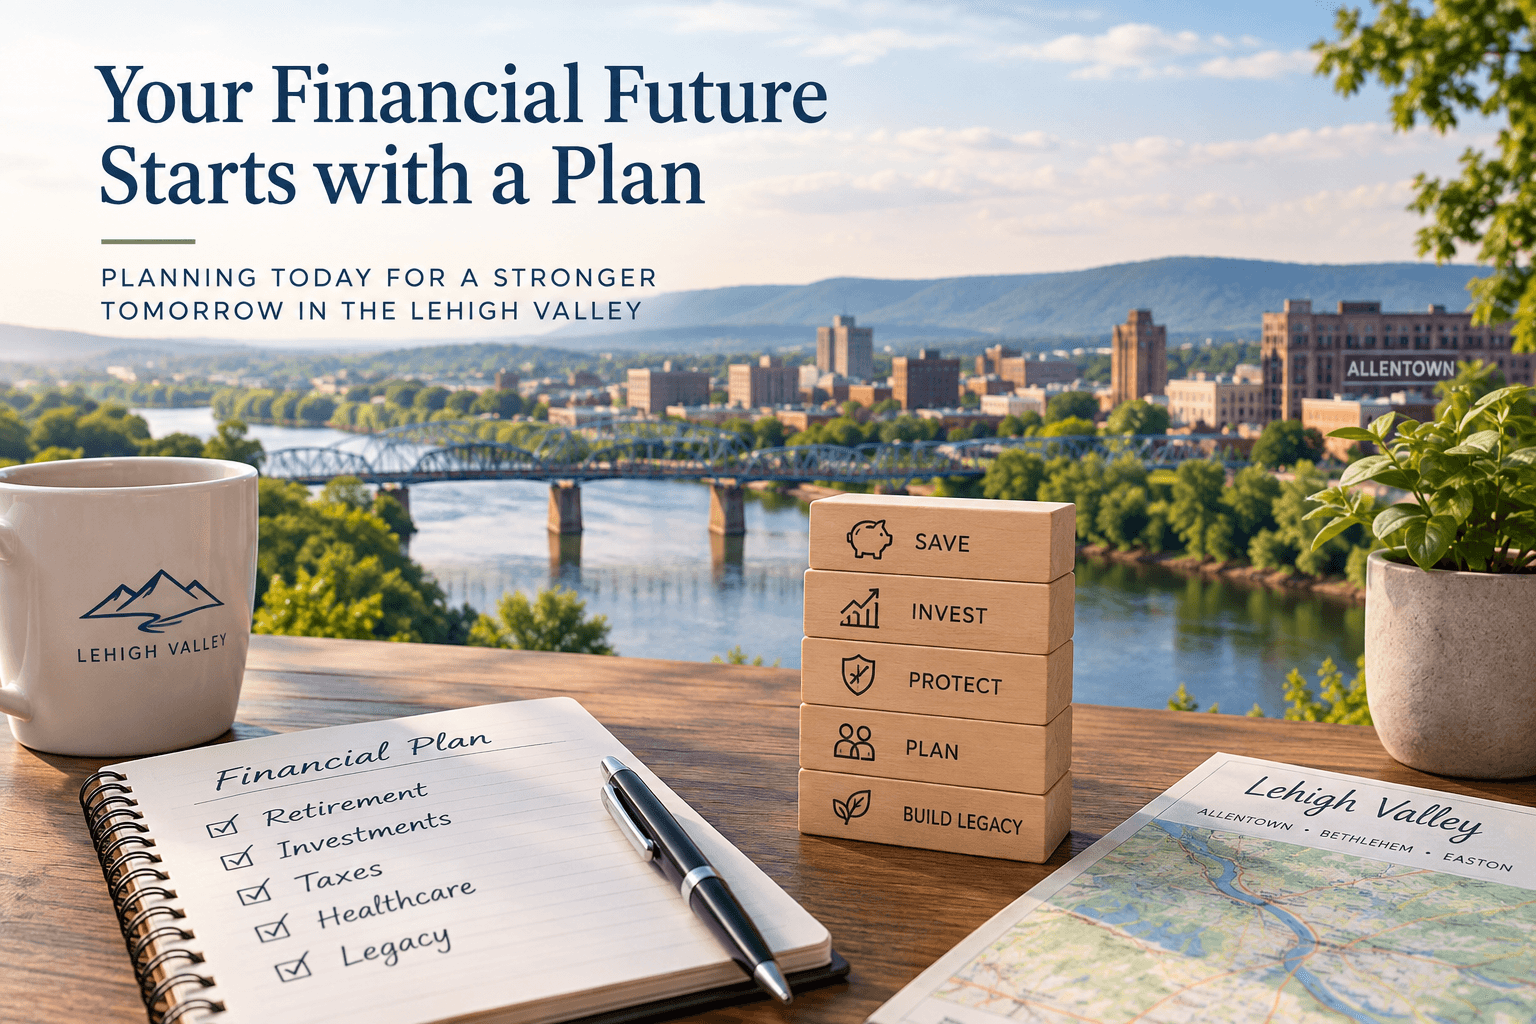
For someone approaching retirement in Allentown, Bethlehem, Easton, or elsewhere in the Lehigh Valley, the process may bring together workplace benefits, retirement accounts, expected income needs, tax considerations, insurance, and estate documents. The mix depends on the household. A medical professional may need to coordinate a demanding career, complex compensation, and retirement timing. A faculty member or administrator may be reviewing 403(b) plan benefits. Another household may be preparing for retirement after a career change or the loss of a spouse.
At Wealthcare of the Lehigh Valley, Financial Planning is one of several service areas that may be considered alongside asset management, income planning, tax planning, risk management, and estate and legacy planning. Planning does not replace legal or tax advice. When those issues arise, they may require coordination with the appropriate professional.
A five-step financial planning process
1. Understand the household picture
The first step is to gather and organize the information that gives context to every later decision. This may include income sources, savings and investment accounts, retirement plans, insurance coverage, debts, recurring expenses, beneficiary designations, and estate documents.
The goal is not simply to create a list of accounts. It is to see how the parts of a household's financial life fit together. For example, a 403(b), a pension election, employer benefits, and a taxable account can each have a different role in a retirement plan.
2. Set priorities and define the questions to solve
With the household picture in view, the next step is to identify the decisions and priorities that matter most right now. Those might include a target retirement date, a move, family support, charitable goals, a concentrated stock position, or how to prepare for a transition in income.
Priorities help shape the questions the plan needs to address. They also make trade-offs clearer. A household may have several worthwhile goals but limited resources or time, so planning can help create an order for evaluating them. See who we help to learn more about the life stages and professional circumstances the firm serves.
3. Evaluate income, tax, and risk considerations
Approaching retirement often changes the questions a household asks. Instead of focusing only on saving, they may need to consider how different income sources, withdrawals, benefits elections, taxes, and insurance coverage fit together.
This stage may include reviewing estimated spending, available sources of retirement income, account ownership, tax characteristics, and the level of investment risk a household is comfortable taking. The purpose is to identify considerations and choices, not to assume one answer fits every household. Tax rules and retirement-plan provisions can change, and personalized tax or legal advice should come from a qualified professional.
4. Implement the agreed-upon steps
After priorities and considerations are evaluated, implementation turns the plan into a working process. Depending on the household, that can include updating account organization, coordinating beneficiary information, reviewing insurance needs, adjusting investment management, or scheduling conversations with tax and legal professionals.
Implementation should be paced to the decisions at hand. Some items may be straightforward administrative tasks. Others may require more analysis or the involvement of other professionals. Our fee schedule explains how Wealthcare of the Lehigh Valley presents its advisory fees.
5. Revisit the plan as circumstances change
A financial plan needs periodic attention because households, markets, employment, tax rules, and personal priorities can all change. A review can be especially useful after a retirement date changes, an employer benefit changes, a family event occurs, or a major financial decision is under consideration.
Revisiting a plan does not promise a particular result. It creates an opportunity to review whether the information, assumptions, and priorities still reflect the household's current situation.
How the process connects to financial planning services
A planning process can help keep separate decisions from being made in isolation. Asset management may address how investments are managed in relation to the overall plan. Income planning can explore retirement income questions. Tax planning, risk management, and estate and legacy planning may each raise related considerations that deserve to be coordinated with the appropriate specialists.
Wealthcare of the Lehigh Valley is a fee-only fiduciary firm. The firm's process is designed to help households organize the financial questions in front of them and make informed decisions based on their circumstances.
A factual next step for Lehigh Valley households
If you are approaching retirement and want to understand what information and decisions may belong in your plan, a first conversation can help clarify the process and the service areas that may be relevant. You can schedule a consultation with Wealthcare of the Lehigh Valley to discuss your household's current situation.
This article is for general educational purposes and is not individualized tax, legal, or investment advice.
Wealthcare of the Lehigh Valley